▶ RSQUARE publishes '2026 H1 Greater Seoul Logistics Market Report: Supply Slowdown and Market Shifts'
▶ New supply down 8% QoQ — "Restricted supply persists following the sharp drop in H1 2025"
▶ Average vacancy rate reaches 12.3% for dry storage and 33.7% for cold storage, extending the downward trend since peaking in H1 2024
The Greater Seoul logistics market continues to work through a lull following the massive supply surge of 2022–2023. Past oversupply and prolonged vacancies have delayed or halted new development, while rising construction costs and stricter warehouse permitting standards have further weakened new supply momentum.
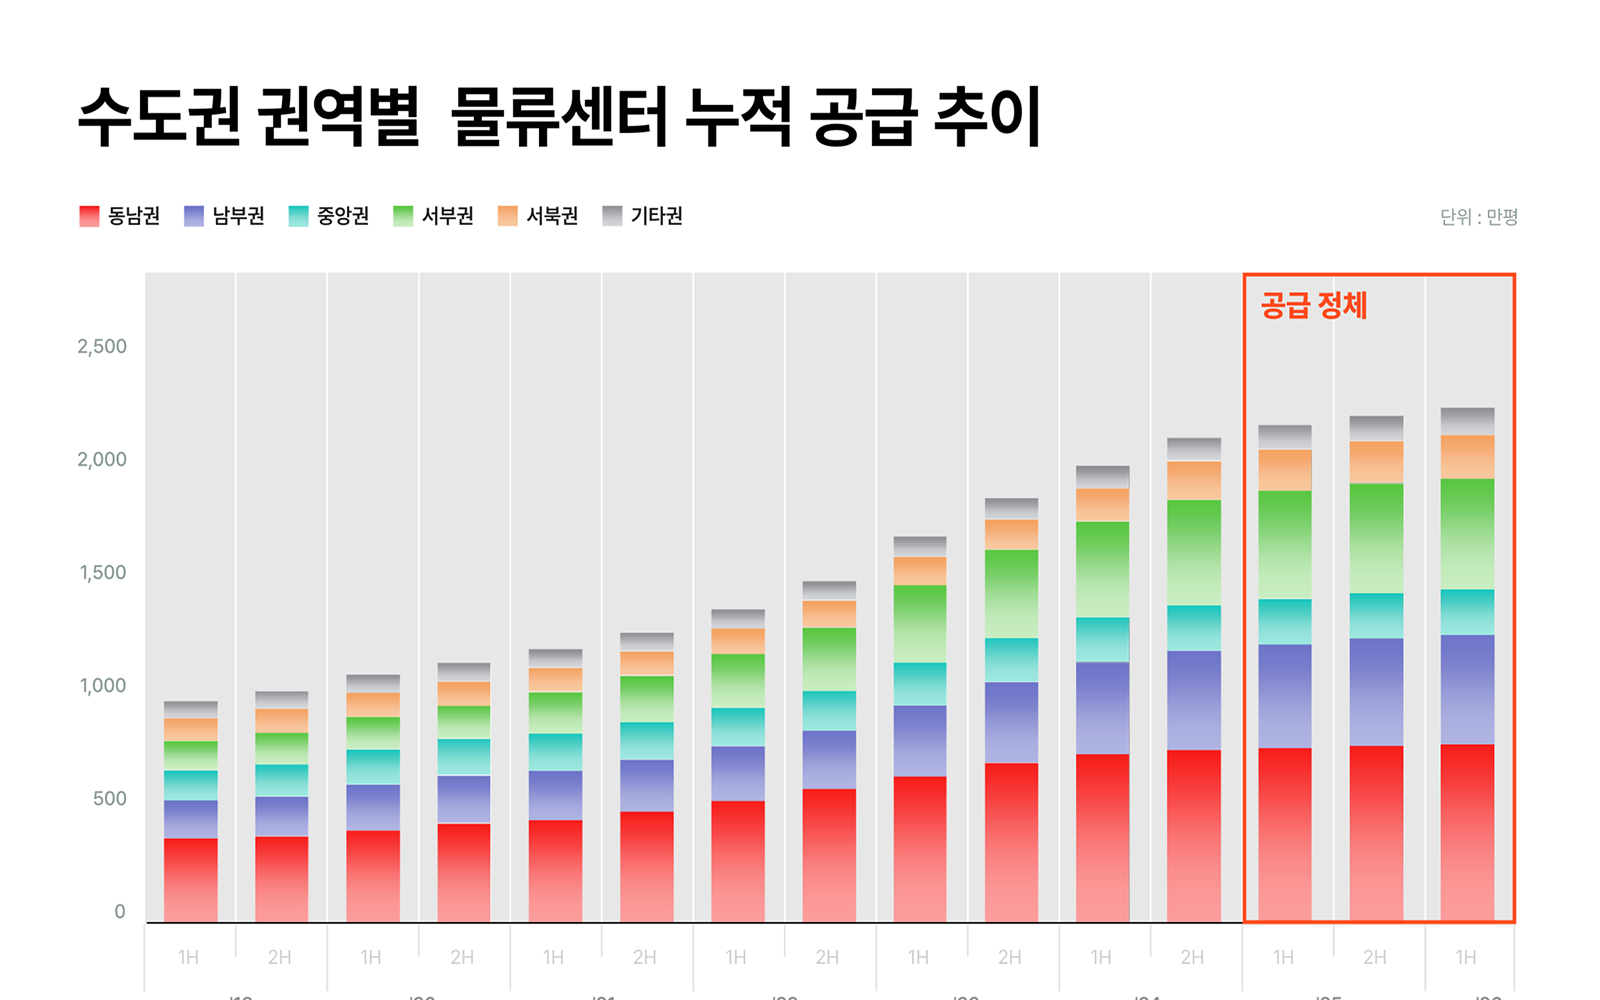
RSQUARE (CEO: Lee Yong-gyun), a full-service commercial real estate firm, released its '2026 H1 Greater Seoul Logistics Market Report: Supply Slowdown and Market Shifts' on the 13th. According to the report, new logistics supply in the Greater Seoul area totaled 175,068 pyeong in H1 2026, down 8% from the previous half-year. After approaching nearly 1 million pyeong in H1 2023, new supply plunged 74% in H1 2025 and has since remained at a reduced, restricted level.
The slowdown in new supply is also reflected in leasing indicators. In H1 2026, average vacancy rates in Greater Seoul stood at 12.3% for dry storage and 33.7% for cold storage — down 1.0 and 2.6 percentage points, respectively, from the previous half-year. Vacancy rates have trended downward since peaking in H1 2024 at 16.8% for dry storage and 41.2% for cold storage.
Nominal rents averaged 33,183 KRW/pyeong for dry facilities and 60,474 KRW/pyeong for cold facilities — up slightly by 470 KRW and 100 KRW, respectively — marking an end to the downward rent pressure that had persisted since H1 2024.
That said, vacancy pressure remained severe for certain cold storage assets. Cold storage vacancy in the Northwest region jumped 7.8 percentage points to 70.0%, the highest vacancy level in Greater Seoul. "RSQUARE noted that this was driven largely by a full vacancy following a major tenant's departure from a Gimpo-based facility."
In the investment market, H1 transaction volume totaled 1.438 trillion KRW, down 59.7% from the previous half-year. This decline largely reflects a base effect following the record-high 3.3 trillion KRW recorded in the prior half-year, with H1 volume landing at roughly 60% of the post-2019 half-year average of 2.3 trillion KRW.
By asset size, medium-sized properties accounted for the majority of deal activity, representing 56% of total transaction volume. The average price per pyeong stood at 6.54 million KRW/pyeong, though individual asset prices ranged widely — from 3.77 million KRW to 12.48 million KRW — depending on property type and location. The largest single-asset deal of the period was the 'Yeongjong Logistics Center Arenas,' which sold for 432 billion KRW.
"A meaningful rebound in new supply is unlikely in the near term," said Sang-jun Lee, Head of the Big Data Consulting Division. "As the supply slowdown continues, close attention should be paid to how vacancies unwind over time."




 \

▶ RSQUARE publishes '2026 H1 Greater Seoul Logistics Market Report: Supply Slowdown and Market Shifts'
▶ New supply down 8% QoQ — "Restricted supply persists following the sharp drop in H1 2025"
▶ Average vacancy rate reaches 12.3% for dry storage and 33.7% for cold storage, extending the downward trend since peaking in H1 2024
The Greater Seoul logistics market continues to work through a lull following the massive supply surge of 2022–2023. Past oversupply and prolonged vacancies have delayed or halted new development, while rising construction costs and stricter warehouse permitting standards have further weakened new supply momentum.
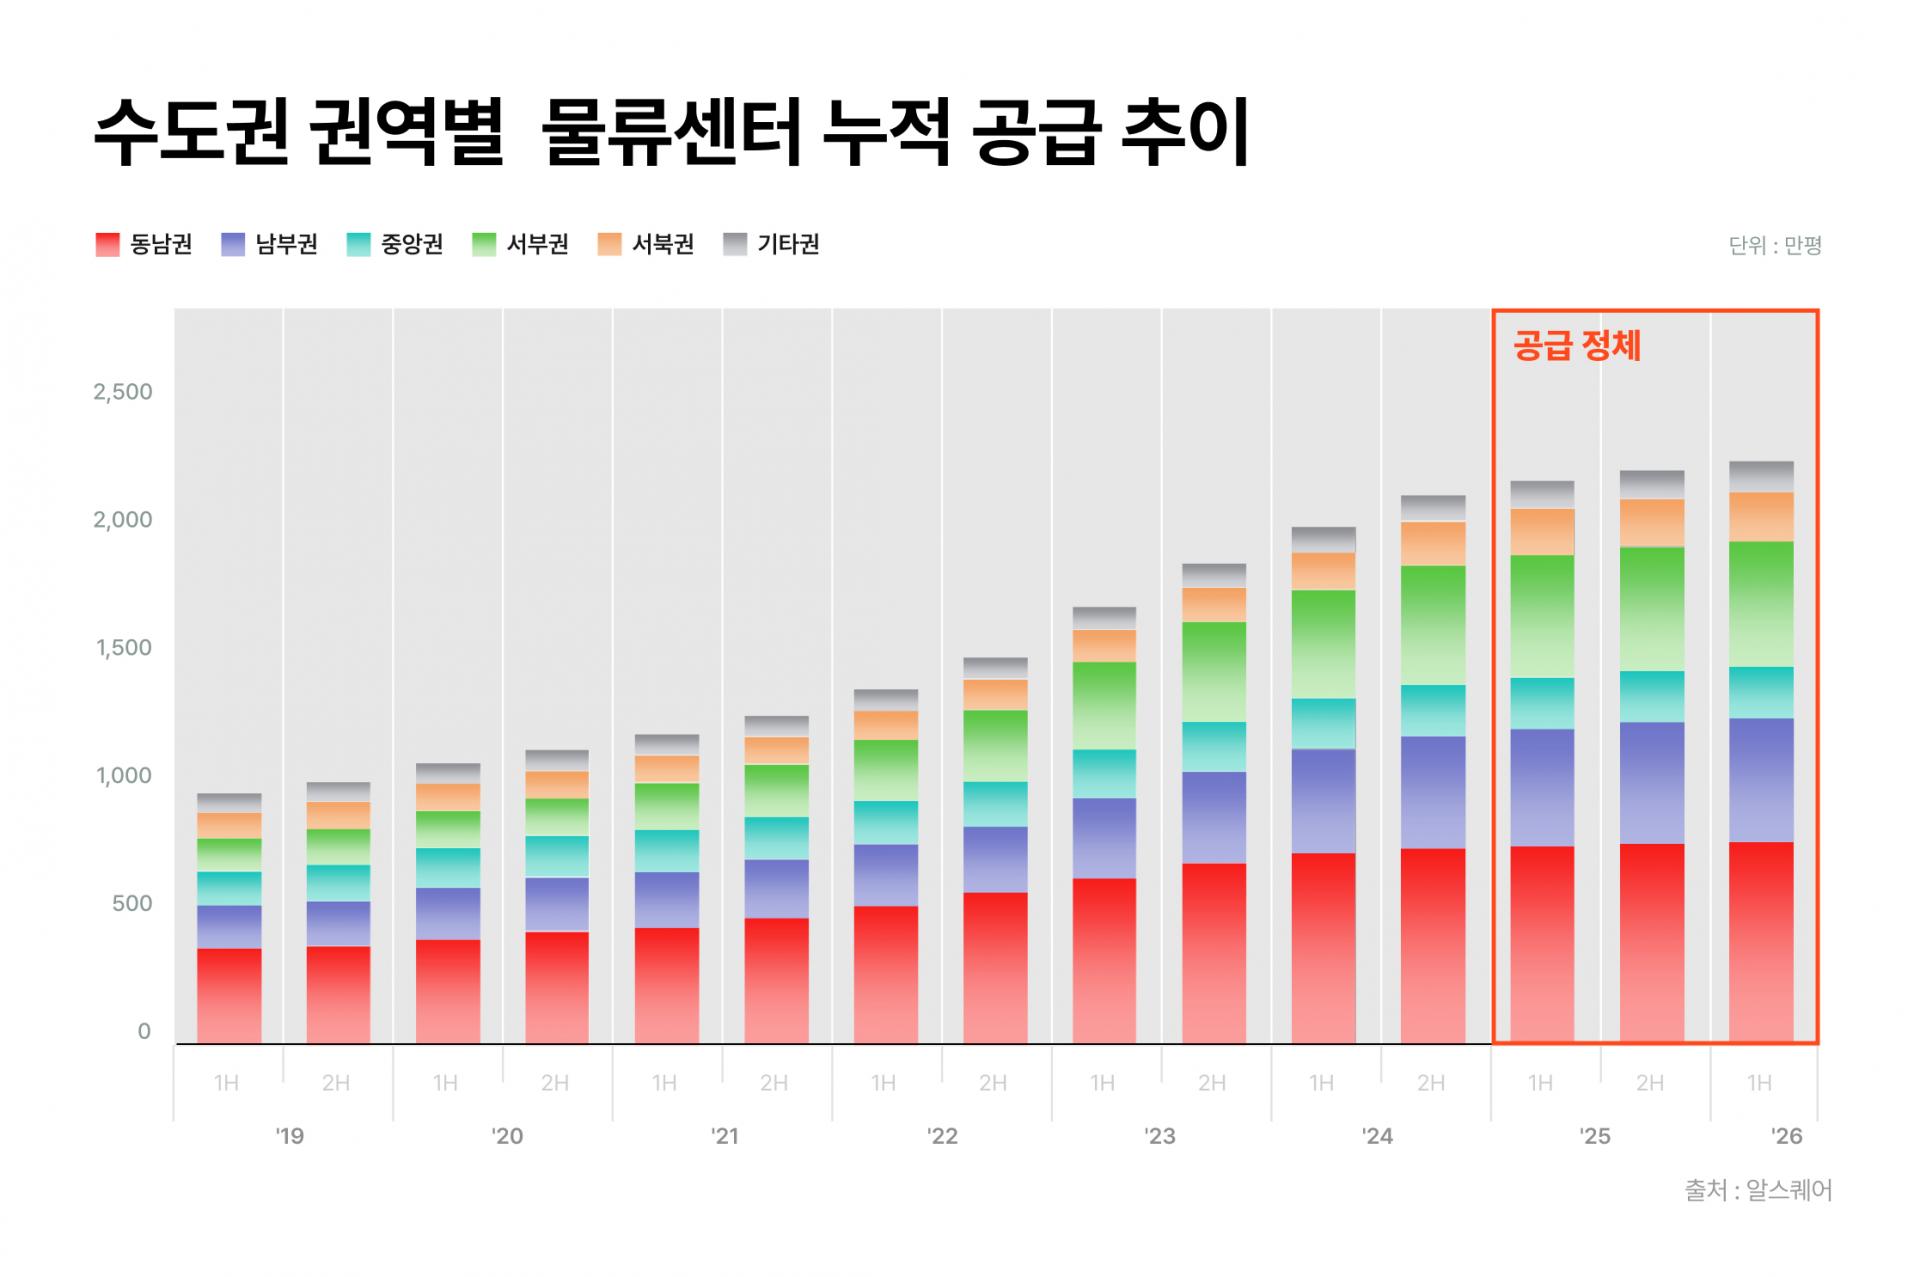
RSQUARE (CEO: Lee Yong-gyun), a full-service commercial real estate firm, released its '2026 H1 Greater Seoul Logistics Market Report: Supply Slowdown and Market Shifts' on the 13th. According to the report, new logistics supply in the Greater Seoul area totaled 175,068 pyeong in H1 2026, down 8% from the previous half-year. After approaching nearly 1 million pyeong in H1 2023, new supply plunged 74% in H1 2025 and has since remained at a reduced, restricted level.
The slowdown in new supply is also reflected in leasing indicators. In H1 2026, average vacancy rates in Greater Seoul stood at 12.3% for dry storage and 33.7% for cold storage — down 1.0 and 2.6 percentage points, respectively, from the previous half-year. Vacancy rates have trended downward since peaking in H1 2024 at 16.8% for dry storage and 41.2% for cold storage.
Nominal rents averaged 33,183 KRW/pyeong for dry facilities and 60,474 KRW/pyeong for cold facilities — up slightly by 470 KRW and 100 KRW, respectively — marking an end to the downward rent pressure that had persisted since H1 2024.
That said, vacancy pressure remained severe for certain cold storage assets. Cold storage vacancy in the Northwest region jumped 7.8 percentage points to 70.0%, the highest vacancy level in Greater Seoul. "RSQUARE noted that this was driven largely by a full vacancy following a major tenant's departure from a Gimpo-based facility."
In the investment market, H1 transaction volume totaled 1.438 trillion KRW, down 59.7% from the previous half-year. This decline largely reflects a base effect following the record-high 3.3 trillion KRW recorded in the prior half-year, with H1 volume landing at roughly 60% of the post-2019 half-year average of 2.3 trillion KRW.
By asset size, medium-sized properties accounted for the majority of deal activity, representing 56% of total transaction volume. The average price per pyeong stood at 6.54 million KRW/pyeong, though individual asset prices ranged widely — from 3.77 million KRW to 12.48 million KRW — depending on property type and location. The largest single-asset deal of the period was the 'Yeongjong Logistics Center Arenas,' which sold for 432 billion KRW.
"A meaningful rebound in new supply is unlikely in the near term," said Sang-jun Lee, Head of the Big Data Consulting Division. "As the supply slowdown continues, close attention should be paid to how vacancies unwind over time."